


There is no single per-trip truck insurance cost in South Africa. Insurers price each trip on exposure, weighing vehicle class, cargo value, route, and driver profile, so your rate moves with every job. As a rough shape: a per-day rate on short-term cover almost always runs higher than an annual premium divided by 365, yet it can still work out cheaper for a genuine one-off trip because you are not paying for 350 days you never drive. Local benchmarks help you frame this. Kweli’s cost-of-running breakdown puts insurance inside the wider per-kilometre cost picture, ArriveAlive tracks the theft and hijacking risk insurers price into premiums, and the SADC transport pillar frames the corridor risk behind cross-border loadings.
Before quoting a job, expect insurers to ask about:
- Driver experience and licence history
- Vehicle class, value, and trailer type
- Cargo type and declared value
- Route, region, and border crossings
- Tracking, security, and parking arrangements
Quick framing: short-term commercial cover is priced as concentrated exposure, not a sliced-up annual rate, which is why a five-day trip costs more per day than a year-long policy averaged out.
Key Takeaways
Per-trip truck insurance cost in South Africa depends on driver profile, cargo value, route risk, and tracking compliance far more than on any fixed rate card.
| Point | Details |
|---|---|
| No fixed per-trip rate | Vehicle class, cargo value, route, and driver profile all move the quote independently. |
| Daily rate beats annual math | Per-day pricing runs higher than a pro-rata annual split, but often costs less for a true one-off trip. |
| Watch the exclusions | Excess levels, towing limits, and downtime cover often matter more than the headline price. |
| Tracking lowers rates | An active, insurer-approved tracker with uptime proof is one of the fastest ways to cut a quote. |
| Pilot before you commit | Truck & Plant On-Demand™ suits intermittent, seasonal, or one-off trips best when tested against real trip data first. |
Table of Contents
- What determines a per-trip truck insurance cost?
- Hidden costs that make a low per-trip quote misleading
- How is a per-trip premium actually calculated?
- How fleet owners lower their per-trip premiums
- Is on-demand per-trip cover the right fit for your operation?
- A fleet manager’s honest view on piloting per-trip cover
- Getting a per-trip quote through Truck & Plant On-Demand™
- Sources
What determines a per-trip truck insurance cost?
Every underwriter works from roughly the same checklist. Understanding it lets you predict, before you even call for a quote, whether a job will land at the cheap end or the expensive end of the range.
Driver profile moves the needle first. A driver with a clean record and years on a specific route class reads as low risk. A newly licenced driver, or one with recent claims, pushes the rate up because inexperience correlates directly with claim frequency.
Vehicle class and trailer type set the base. A rigid box truck rates differently to an articulated tractor pulling a tri-axle trailer, mostly because replacement cost and rollover risk differ sharply between the two.
Cargo type and declared value matter as much as the truck itself. Electronics, copper, and fuel attract higher loadings because they are frequent hijacking targets, a risk ArriveAlive documents in detail for South African fleets. A basic guide to cargo insurance is worth reading if you have never had to declare a cargo value before.
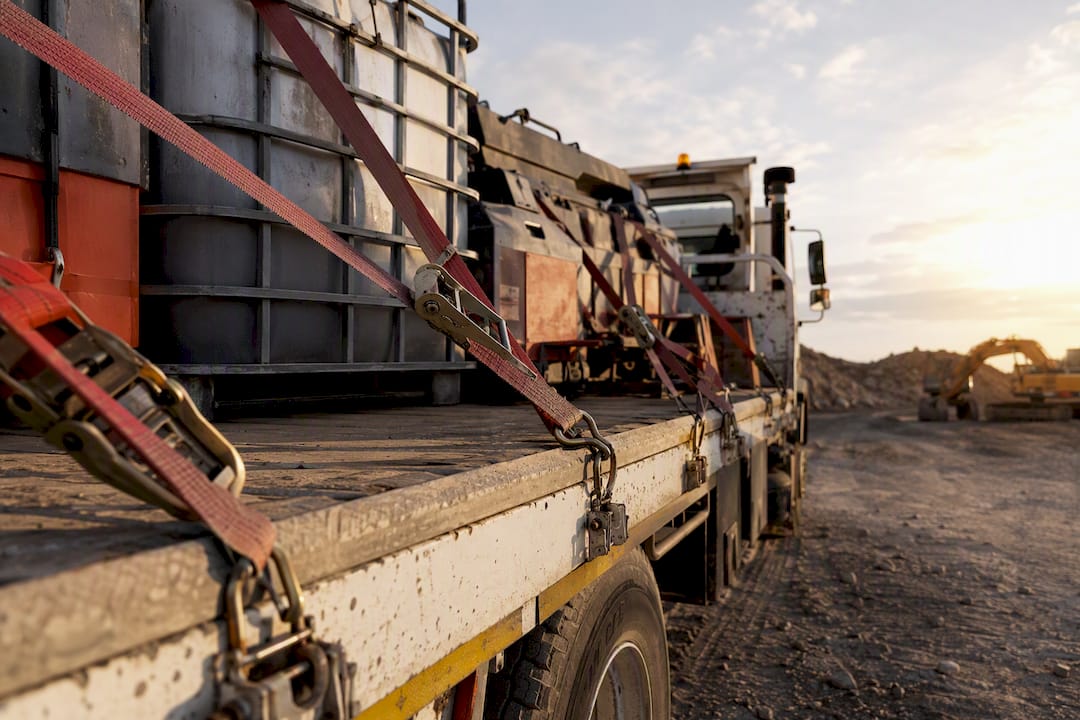
Route and corridor risk can swing a quote more than any other single factor. A local delivery inside a low-crime urban zone rates far lower than a cross-border run through a known hijacking corridor, a distinction ArriveAlive’s hijacking data makes explicit.
Other levers that shift the number:
- Time on road: night driving and multi-day trips add loadings for fatigue and reduced visibility risk.
- Security controls: secured depot parking, immobilisers, and CCTV typically earn a discount.
- Tracking and telematics: an active, insurer-approved tracker with proof of uptime often unlocks a lower rate.
- Policy limits and excess: raising your excess or capping your indemnity limit both lower the headline per-trip figure.
Pro Tip: Photograph your tracker’s active status and your depot’s security setup before you request a quote. Insurers respond faster, and more favourably, to proof than to a promise.
Hidden costs that make a low per-trip quote misleading
A cheap headline rate can hide a far more expensive policy. Before comparing two quotes on price alone, check these five areas:
- Excess structure. A low premium paired with a high excess shifts risk back onto you. If your excess is 15% of a rig’s value, a single claim can cost more than a year of premiums saved.
- Towing, recovery, and salvage. Many per-trip policies sub-limit or exclude recovery costs entirely, leaving you to pay for a breakdown recovery on a remote stretch of the N1 out of pocket.
- Downtime and loss-of-income cover. A truck off the road for repairs earns nothing. Few basic per-trip policies compensate for that lost income, so check whether it is even offered as an add-on.
- Conditional triggers. Some policies only pay out if your tracker stayed active the whole trip or if the driver behind the wheel matches an approved list submitted at inception. Miss either condition, and a legitimate claim can be declined.
- Administrative and documentation fees. Cross-border trips often carry extra paperwork charges, and some insurers cap claims per trip regardless of the loss, a detail worth checking against Kweli’s cost breakdown before you sign.
Read every exclusion clause on a per-trip quote as carefully as the price. The number on the quote page is only half the cost.
How is a per-trip premium actually calculated?
Two quick examples show how the underwriting checklist plays out in practice.
Example 1: local haul, light box truck. A four-tonne box truck running a same-day delivery inside a metro area, low-value general goods, an experienced driver, and an active tracker. This profile sits at the low end of the per-trip range because every risk factor is contained: short duration, familiar route, low cargo value.
Example 2: cross-border haul, heavy tractor. A tri-axle tractor-trailer carrying high-value electronics through a SADC corridor over three days, with a night-driving segment included. Corridor risk, cargo value, and extended time on the road all stack loadings on top of the base rate, and insurers will usually require proof of an insurer-approved tracker and a documented driver list before binding cover.
The pricing shape stays consistent across both: short-term rates run higher per day than an annual policy’s pro-rata equivalent, but for a genuine one-off trip that is still the cheaper outcome overall. Fold the insurance line into your per-kilometre costing the same way you would fuel or tyres, using a local reference like Kweli’s running-cost figures, so you never underbid a load because you forgot to price the risk.
How fleet owners lower their per-trip premiums
Cost control on per-trip cover comes down to a handful of repeatable habits, not a single trick.
- Keep tracking active and provable. Submit uptime reports where your insurer allows it. A verifiable tracking record is one of the fastest ways to earn a lower rate on repeat business.
- Route around known risk corridors. Where a safer alternative exists, choosing it over a flagged high-crime route can materially change a quote.
- Avoid unnecessary night moves. If a trip can be scheduled to avoid a night-driving segment, do it. The loading saved often outweighs the extra day of transit time.
- Vet and train drivers deliberately. A driver incentive scheme tied to claims-free periods reduces frequency, which is the single biggest lever insurers respond to over time.
- Bundle where you can. Grouping several short trips into a temporary multi-trip block usually lowers the unit rate compared to quoting each leg separately.
- Negotiate your excess. Adjusting the excess structure, or declaring cargo value accurately rather than defensively high, both bring the quoted rate closer to your real risk.
Pro Tip: Keep a simple spreadsheet of every per-trip quote you receive, broken down by route, cargo, and driver. After ten or so trips, you will see your own risk pattern more clearly than any insurer’s questionnaire can capture.
Is on-demand per-trip cover the right fit for your operation?
Truck & Plant On-Demand™ prices exposure into the trip itself rather than spreading a flat cost across twelve months you may not need. That distinction is exactly why on-demand cover suits certain operating patterns better than a standard annual policy.
It tends to make the most financial sense when your operation looks like one of these:
- Intermittent work: a subcontractor called in for occasional loads
- Seasonal fleets: harvest runs, construction peaks, or holiday freight spikes
- Rented or hired-in vehicles used for a defined job
- A one-off high-value load that does not justify a year of cover
Insurers writing short-term or per-trip cover in South Africa generally expect the same operational basics: an active, insurer-approved tracker, a documented driver list, and route information submitted before the trip starts. Truck & Plant On-Demand™ builds its application flow around exactly those requirements, so operators are not scrambling to assemble documentation trip by trip.
Test the model before committing to it fully. Run a small pilot, three to five trips on a defined corridor, track claims and downtime against what an annual pro-rata cost would have been, then decide.
That comparison, done honestly over a real sample of trips, tells you more than any calculator ever will.
A fleet manager’s honest view on piloting per-trip cover
Every insurance decision is a trade between risk and cost, and per-trip cover is no exception. If you are weighing it, do not guess. Run one truck, or one corridor, for three months. Log every claim, every day of downtime, every quote. Compare that against what an annual policy would have cost across the same period. The numbers will tell you more in twelve weeks than any spreadsheet built on assumptions.
— Coert
Getting a per-trip quote through Truck & Plant On-Demand™
Truck & Plant On-Demand™ covers commercial vehicles, trailers, and plant machinery on a pay-for-use basis, with cargo, liability, and machinery breakdown options available for South African operators who need cover shaped around a single trip, not a fixed year.

To get an accurate quote, have this ready before you apply:
- Vehicle details: class, value, and trailer configuration
- Driver information: licence class and experience
- Route: origin, destination, and any border crossings
- Cargo type and declared value
Digital claims management means you are not stuck on hold after an incident, and cover can flex up or down as your next job changes shape. If your business runs intermittent trips, seasonal peaks, or one-off high-value loads, comparing on-demand and annual pricing models side by side is worth the ten minutes it takes. Request your quote directly through the Truck & Plant On-Demand™ fleet insurance page and get a number matched to your actual trip, not a generic annual estimate.
Sources
- Cost of Running a Truck in SA 2026: R14/km Full Breakdown
- Fleet-Insurance and Truck Insurance for Commercial Vehicles
- SADC transport pillar
- Temporary Commercial Vehicle Insurance: Short-Term Coverage