


For most small, stable fleets with the same drivers month after month, named-driver cover saves real money and stays easy to manage. Once your driver pool turns over often, or you rely on agency and pooled drivers, a tightly constrained any-driver rule or a hybrid setup usually earns back its extra premium in flexibility. There is an alternative option that offers cover which flexes with your operations instead of locking you into either model year round.
TL;DR:
- The typical cost difference ranges from 20 to 40 percent higher for any-driver coverage compared to named-driver policies, depending on risk factors.
- Tightening eligibility requirements, requesting comparable quote comparisons, and using risk mitigation discounts can help reduce the premium gap.
- Proper documentation and verification of driver authorization, license status, and vehicle assignment are crucial to avoid claim disputes regardless of the policy type.
- Fleets with low turnover and stable driver rosters benefit from named drivers, while high-turnover or seasonal fleets often need more flexible hybrid or on-demand options.
- On-demand insurance that scales with actual usage can better match fluctuating fleet needs, especially for seasonal surges or short-term hires.
Table of Contents
- Any driver vs named driver: the operational trade-offs
- What any-driver cover actually costs versus named-driver
- Running the day-to-day: claims risk and paperwork that matter
- How to choose the right driver basis for your fleet
- Pre-bind to post-bind: a checklist that reduces disputes
- Two setups that got it right, and one lesson that ties them together
- Flexible cover that matches how your fleet actually runs
- Sources
Any driver vs named driver: the operational trade-offs
Any-driver wording lets any eligible driver operate your scheduled vehicles, but “eligible” carries conditions. Insurers set minimum age bands, license-held minimums, acceptable driving records, and require documented company authorisation before that flexibility applies. Miss the paperwork and a claim can get contested even when the driver was genuinely on the clock for you.
Named-driver policies flip that logic. You list every authorized person by name, and insurers price to what they know about each individual. That’s why named-driver is often cheaper for small, stable fleets with low turnover. The catch is admin: every new hire, every departure, every licence change means updating the policy schedule.
Here’s how the two stack up in practice:
- Any-driver: higher premium, lower admin, better fit for high-turnover or pooled operations.
- Named-driver: lower premium, higher admin, better fit for small, consistent driver rosters.
- Hybrid: named entries for higher-risk or specialist operators, any-driver criteria for the rest of the pool.
Hybrid setups are common precisely because most fleets aren’t purely one or the other. A construction firm might name three senior operators while running everyone else under an any-driver rule with a minimum age and clean MVR requirement.
What any-driver cover actually costs versus named-driver
Underwriters price any-driver higher because they’re insuring uncertainty, not a known list of people. The main levers are eligible-driver risk, vehicle class, operating territory, the limits and deductibles you choose, and your loss history.
The typical gap runs 20 to 40 percent higher for any-driver cover on otherwise comparable terms, according to market commentary tracked by Quotezone. That range moves depending on your fleet’s claims history and how tightly you restrict eligibility, so treat it as a starting point for negotiation, not a fixed number.
Three steps narrow that gap and give you numbers you can actually trust:
- Tighten eligibility first. Raising the minimum age, requiring more years licensed, or setting a clean MVR standard is often the fastest way to bring any-driver pricing closer to named-driver levels.
- Request identical quotes. Ask for named-driver, any-driver, and hybrid pricing on the same limits, deductibles, and vehicle schedule so you’re comparing real numbers, not apples to oranges.
- Credit your mitigations. Telematics, formal driver training, and secure off-street parking are commonly recognised by insurers as discounts on either policy type.
Running the day-to-day: claims risk and paperwork that matter
The policy type you choose sets the paperwork you need to run every day, and skipping it is where claims disputes start.
Any-driver setups need pre-shift and hiring discipline: a regular MVR check cadence, a documented minimum age policy, and a signed authorisation on file for anyone who touches a scheduled vehicle. Underwriters expect proof the driver met your eligibility rules at the moment of the loss, and missing that proof is one of the most common triggers for a contested claim.
Named-driver setups shift the workload to your policy schedule. Every driver change, new hire, or licence update needs to reach your insurer through your broker portal, ideally before that driver gets behind the wheel, not after an incident.
Whatever model you run, a claim packet needs the same core evidence:
- Who was driving, confirmed against your records.
- Proof of authorisation at the time of the incident.
- An MVR snapshot showing that driver met your eligibility standard.
- Vehicle assignment or pooled-vehicle sign-out records.
Agency and temporary drivers complicate both models. If you bring in temp staff at short notice, separate short-term cover or a carefully worded any-driver clause is often the more practical route than trying to name every casual worker.
Pro Tip: Keep your MVR checks and authorisation signatures in one shared log, not scattered across HR files and email threads. When a claim lands, you want that evidence pulled in minutes, not days.
How to choose the right driver basis for your fleet
Pick a driver basis the way you’d size any other operating cost: measure your actual usage pattern before you commit to a model.
- Map your churn and vehicle allocation. Count how often drivers change, and note whether vehicles are assigned to individuals or shared across a pool.
- Assess your admin capacity. If nobody owns updating driver schedules promptly, named-driver’s savings get eaten by lapses in coverage.
- Request comparable quotes. Get named-driver, any-driver, and hybrid pricing with identical limits, deductibles, and vehicle lists so the numbers mean something.
- Calculate total cost of ownership. Add the admin hours and any short-term or temp cover you’d need on top of the base premium, not just the sticker price.
- Set eligibility rules and an audit cadence. If any-driver wins out, decide now what age, licence, and MVR standards apply, and how often you’ll check them.
| Fleet profile | Likely fit | Why |
|---|---|---|
| Small, stable crew, low turnover | Named-driver | Lower premium, admin load is manageable |
| High turnover or seasonal hiring | Any-driver (tight eligibility) | Flexibility outweighs the premium gap |
| Mixed fleet, few specialist operators | Hybrid | Named entries for key roles, any-driver for the rest |
| Heavy reliance on agency/temp drivers | Any-driver or short-term cover | Naming every casual worker isn’t practical |
Pre-bind to post-bind: a checklist that reduces disputes
Getting the driver basis right on paper is only half the job. What you document before and after a claim decides whether that cover actually pays out cleanly.
Before you bind the policy:
- Document permitted use and your authorisation process in writing.
- Set minimum age and license-years thresholds if you’re going any-driver.
- Confirm your insurer’s MVR standard and how often it needs rechecking.
Before every shift:
- Verify MVR status on the cadence your policy requires.
- Run spot checks on driver authorisation records, not just at onboarding.
- Log every authorisation entry the moment it happens, not retroactively.
After an incident:
- Assemble the claim packet immediately: driver identity, authorisation proof, MVR snapshot, vehicle assignment record.
Ongoing:
- Keep driver training current and tied to your renewal cycle.
- Assign one person ownership of the MVR and portal update process, so it doesn’t fall through the cracks between hires.
Pro Tip: Review your policy wording on permitted use at least once a year, not just at renewal. Operations change faster than paperwork does, and a stale permitted-use clause is an easy way to void a claim you thought you had covered.
Two setups that got it right, and one lesson that ties them together
Commercial vehicle and plant insurance rewards discipline more than it rewards clever policy structuring. I’ve seen fleets talk themselves into the cheaper option on paper and then lose the savings the first time a claim gets questioned over missing authorisation records.
One small plant-hire operator I’d point to as a model ran three core machine operators under a named-driver policy and layered short-term temp cover on top for busy seasons. Their admin stayed light because the roster barely moved, and the temp cover meant they never had to name a casual hire they’d use for two weeks.
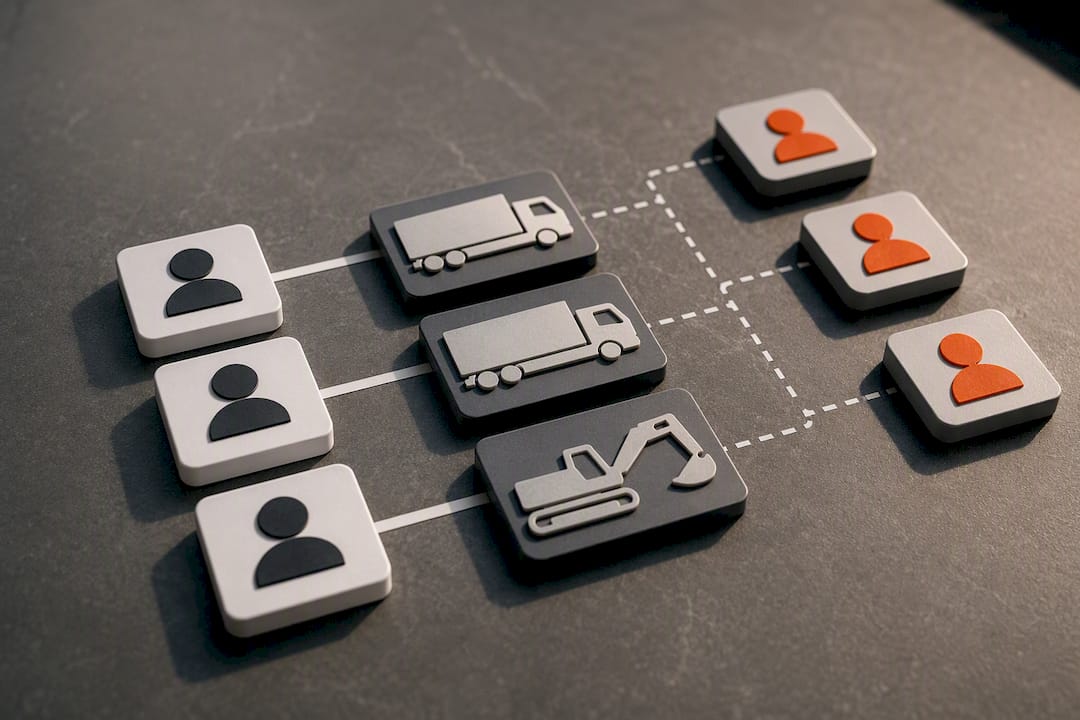
A rental and hire operator running a larger pooled fleet took the opposite route: strict any-driver criteria (minimum age, licence years, clean MVR) backed by a shared audit log every dispatcher could see before handing over keys. Their premium ran higher than a comparable named-driver policy, but they never lost a claim to a documentation gap.
The discipline that separates both from fleets that get burned is the same: keep an MVR and authorisation audit trail that’s current, not reconstructed after the fact. Everything else in this decision is negotiable. That habit isn’t.
— Coert
Flexible cover that matches how your fleet actually runs
Choosing between named-driver and any-driver assumes you’re locked into one annual structure for twelve months. Some on-demand insurance options allow you to adjust cover as your driver pool, vehicle count, or project mix changes, instead of paying a flat any-driver premium year round to cover flexibility you only need part of the time.

That matters most for fleets with seasonal surges, agency drivers on short notice, or plant machinery that sits idle between projects. Rather than carrying a permanent any-driver premium to handle the odd temp hire, you can scale short-term cover on for the weeks you actually need it and scale it back off. It’s the same logic behind comparing annual and on-demand cover: pay for the risk profile you actually run, not the one your policy assumes by default.
If you’re weighing named-driver against any-driver right now, request an apples-to-apples quote through Truck & Plant On-Demand™ and see how short-term, usage-based cover compares against a full annual any-driver premium for your actual fleet.
Sources
- Any Driver Fleet Insurance: 5 Rules + 2026 Costs
- Fleet Insurance Guide for Business Owners | Forum Insurance
- Any-Driver vs Named-Driver Fleet Insurance | Quotezone
- Any driver vs named driver van insurance for small firms